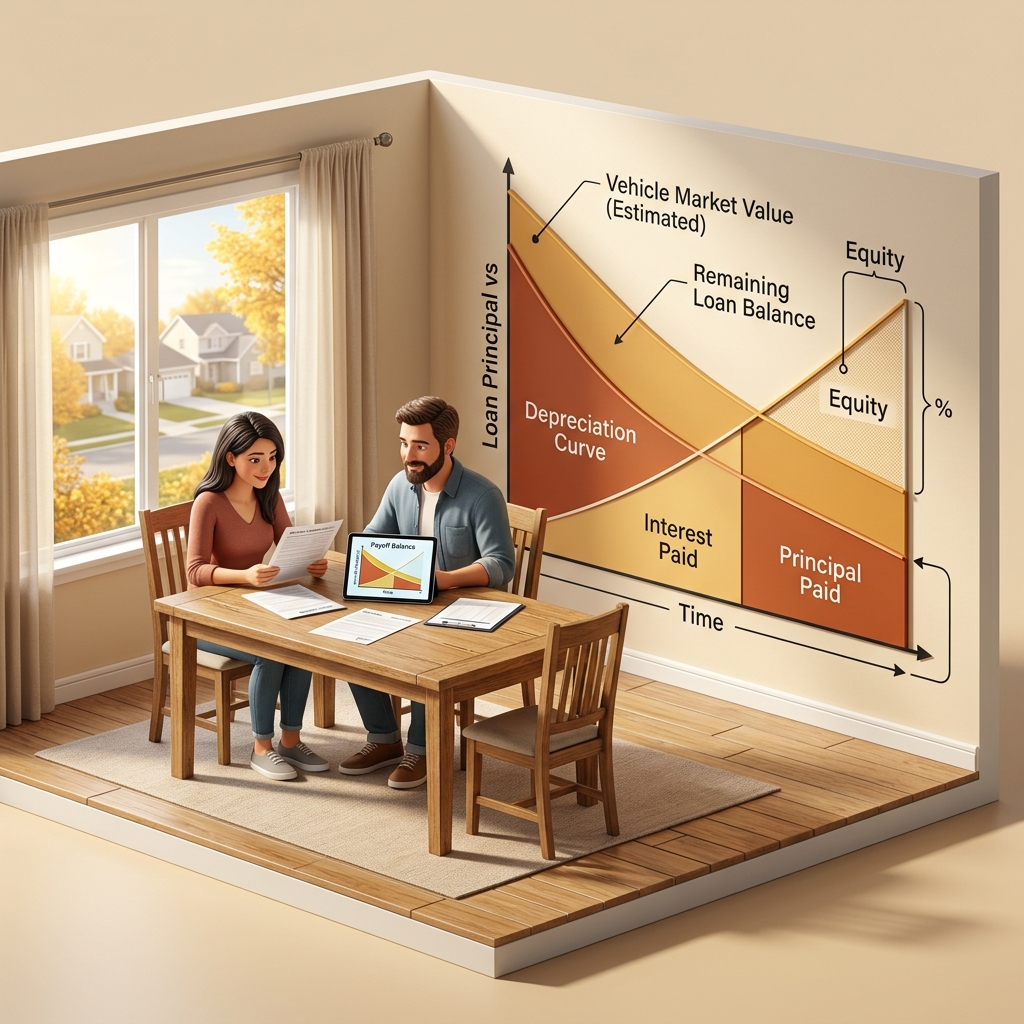
You can get out of a negative equity auto loan by paying the financial difference between your outstanding payoff balance and fair market value in cash, applying extra payments directly to the loan principal to build positive equity, or selling the vehicle directly to clear the lien. Alternatively, refinancing at a lower interest rate or rolling the shortfall into a replacement vehicle loan can restructure the balance, though paying the shortfall directly avoids adding debt.
Managing an underwater vehicle balance requires understanding your exact payoff amount before choosing a path forward. An upside-down car loan happens when initial vehicle depreciation outpaces early loan payments, leaving a gap between what the car is worth and what is owed. For drivers navigating daily suburban drives through Boardman Township, evaluating loan options starts with requesting an official 10-day payoff quote from your lender. Our team at 7871 Market St can help you evaluate your current vehicle value and calculate your exact payoff standing. If you want to discuss your payoff balance with an appraisal specialist, you can also give our team a quick call to walk through your options.
Table of Contents
- What Does Having an Upside-Down Car Loan Mean and How Is LTV Calculated?
- Can You Sell a Car in Boardman When Owing More Than Fair Market Value?
- Is Refinancing Better Than Selling an Underwater Vehicle or Making Extra Payments?
- Frequently Asked Questions About Selling Upside-Down Auto Loans
- Sell Your Vehicle and Clear Your Loan Balance at Ken Ganley Buying Center
What Does Having an Upside-Down Car Loan Mean and How Is LTV Calculated?
Having an upside-down car loan means owing more money on your auto loan than the vehicle is worth on the open market, creating negative equity. Your loan-to-value ratio (LTV) is calculated by dividing your total remaining loan balance by the vehicle’s fair market value and multiplying by 100.
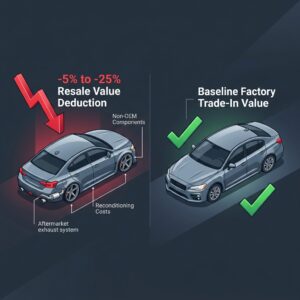
If your remaining loan balance is $20,000 and your vehicle’s appraised market value is $16,000, you have $4,000 in negative equity, resulting in an LTV ratio of 125%. Financial institutions use LTV to evaluate lending risk during refinancing or new vehicle purchases. Most vehicle loans remain upside down for the first two to three years of a standard 60-month term because initial depreciation occurs faster than early principal reduction.
The structure of your auto financing impacts how quickly you build equity. Most auto loans utilize a simple interest rate where interest accumulates daily based on the remaining principal balance, meaning every extra dollar paid directly reduces future interest charges. In contrast, loans with precomputed interest calculate total interest charges upfront at contract signing, making early paydowns far less effective at reducing total borrowing costs. Drivers commuting through Youngstown along the Mahoning Valley often find that vehicles equipped with all-wheel drive maintain stronger resale value during regional winter conditions, helping narrow the equity gap faster than front-wheel drive models. Browsing our pre-owned vehicle selection can give you a clear benchmark of current market values for comparable models.
Can You Sell a Car in Boardman When Owing More Than Fair Market Value?
You can sell a vehicle even if you owe more than its current fair market value, provided the active lien is fully satisfied at the time of sale. To complete the sale and transfer ownership legally, the seller or acquiring business must submit the total loan payoff amount to the financial institution holding the title.
Selling an underwater vehicle to a dedicated buying center eliminates the friction commonly associated with private sales. Private buyers are often hesitant to hand over funds while a financial institution retains the physical title, and the seller must cover the cash shortfall immediately to release the lien. In Ohio, a lienholder must officially release its interest on the vehicle title—either by stamping the physical paper title or updating the Electronic Lien and Title system—before a clean title can be issued. The buyer then has 30 days from the date of purchase to take the assigned title to a county Clerk of Courts title office, pay applicable sales tax, and complete registration.
When you bring your vehicle to our acquisition department, our inventory team contacts your lender directly to obtain an official 10-day payoff quote. If your vehicle’s appraised instant cash offer is $15,000 and your loan balance is $17,000, you can pay the remaining $2,000 shortfall using certified funds or a card during the transaction. Our specialists then remit the full $17,000 to your lender, clearing the lien and transferring the title efficiently. Reviewing our selling process guide walks you through every step required to handle title paperwork and lender communications.
Is Refinancing Better Than Selling an Underwater Vehicle or Making Extra Payments?
Refinancing is better than selling if you intend to keep your vehicle and can secure a lower interest rate, but making extra principal payments is the fastest way to build equity without paying transaction costs or origination fees. Selling an underwater vehicle makes sense primarily when monthly payments are unsustainable and you can cover the remaining equity shortfall immediately.
Refinancing an upside-down loan presents specific hurdles because financial institutions enforce strict LTV caps, usually limiting refinancing to between 100% and 125% of the vehicle’s fair market value. If your loan balance significantly exceeds that threshold, lenders require an upfront cash payment to lower the principal before approving a lower interest rate. If you qualify for refinancing, shortening your remaining loan term or securing a lower rate reduces the portion of your monthly payment going toward interest, accelerating your path toward positive equity.
For owners who plan to retain their vehicle, applying extra principal payments directly to an active simple interest loan is often the most cost-effective financial strategy. Because simple interest accrues daily based on your outstanding principal balance, making additional payments earmarked strictly for the principal reduces daily interest accumulation immediately. Adding $100 or $150 to your monthly payment shortens your loan term and shrinks your negative equity balance without requiring new credit applications or title processing.
Frequently Asked Questions About Selling Upside-Down Auto Loans
Q: Does gap insurance pay off negative equity when I sell or trade in my car?
Gap insurance is designed exclusively to protect owners when a vehicle is declared a total loss due to an accident or theft. It pays the difference between the vehicle’s actual cash value and the remaining loan balance at the time of the loss. Gap insurance does not cover negative equity during a routine vehicle sale, trade-in, or voluntary loan payoff. Additionally, many gap policies specifically exclude any prior negative equity that was rolled over from a previous auto loan.
Q: Can personal loans be used to clear negative equity shortfall on a car sale?
An unsecured personal loan can be used to pay off the remaining equity shortfall when selling an underwater vehicle. This strategy allows you to clear the auto loan lien, release the vehicle title to the buyer, and eliminate auto insurance requirements on that vehicle. However, personal loans generally carry higher interest rates than auto loans, so it is essential to calculate total borrowing costs before choosing this option.
Q: How long does a standard auto loan typically remain upside down?
Most auto loans remain upside down for the first two to three years of a standard 60-month term. This occurs because new and late-model vehicles experience their steepest market depreciation during the first few years of ownership, while early amortized loan payments primarily cover accrued interest charges rather than loan principal.
Q: What documentation do I need to bring to sell a car with an active loan?
To sell a vehicle with an active loan, you must bring a valid state-issued photo ID for all listed title owners, current vehicle registration, all original factory keys and key fobs, and your current loan account details. Having your account number and lender contact information allows appraisers to pull an official 10-day payoff quote directly from the bank during your visit.
Q: How does a simple interest auto loan differ from precomputed interest when paying off early?
Simple interest auto loans calculate interest daily based on your current principal balance, meaning paying extra toward your principal directly reduces total interest owed over time. Precomputed interest loans calculate the total interest for the full term upfront and divide it evenly into monthly payments. Paying off a precomputed loan early yields fewer interest savings compared to a simple interest loan. Drivers seeking more details on appraisal paperwork or equity calculations can review our complete FAQ hub for additional insights.
Sell Your Vehicle and Clear Your Loan Balance at Ken Ganley Buying Center
Selling an upside-down vehicle does not have to be a complicated or stressful process. At Ken Ganley Buying Center Boardman, our appraisal team provides physical vehicle evaluations and handles all lender payoff paperwork on the spot. Whether you want to pay off your equity gap and walk away with a cleared title or explore your options for a replacement vehicle, we offer cash purchase transactions and transparent processing. You can visit our location on Market Street today to receive a firm written quote, give our team a quick call to discuss your payoff details, or access our main buying center portal to get started online.
© 2026 Ken Ganley Buying Center Boardman. All rights reserved.
While every effort has been made to ensure the accuracy of the information displayed on this website, the vehicle values, offers, and listings shown may not reflect all accurate vehicle details or current market conditions. Vehicle photos may be representative only and may not match the actual vehicle. All offers, appraisals, and transactions are subject to vehicle inspection, verification, and prior sale. Final purchase amounts may vary based on condition, equipment, history, and market factors. Please contact the Dealership for complete details and confirmation.